Borrowing capacity is how much a lender is willing to lend you, based on your income, expenses, debts and the property you plan to buy. It is one of the first numbers people look up, and one of the most misunderstood.
Online calculators are a starting point
A calculator gives a rough idea, but it cannot see everything a lender looks at. Two people on the same salary can get very different answers once their spending, existing loans and credit limits are counted.
It changes from lender to lender
Each lender assesses applications its own way, including how it treats rental income and the buffer it adds to interest rates. That is why the same person can get different answers from different banks. A mortgage broker can compare lenders for you.
Investing is assessed differently from buying a home
Your borrowing capacity for an investment property can differ from what you could borrow for a home you live in. Expected rent may be counted, but usually only part of it, and the loan terms can differ. If you are weighing up a home first or an investment first, ask for both numbers.
What brings it down
Paying down or closing debts you no longer need can make a real difference before you apply.
Deposit and up-front costs matter too
Borrowing capacity is only half the picture. You also need a deposit and funds for up-front costs such as stamp duty, lender fees and, in some cases, lenders mortgage insurance. These can be lower than people expect, depending on the state, the property type and the loan.
Equity can help
If you own a home, the gap between its value and what you owe is your equity. Some lenders let you use part of it towards the deposit on your next purchase. How much you can access is the lender's decision.
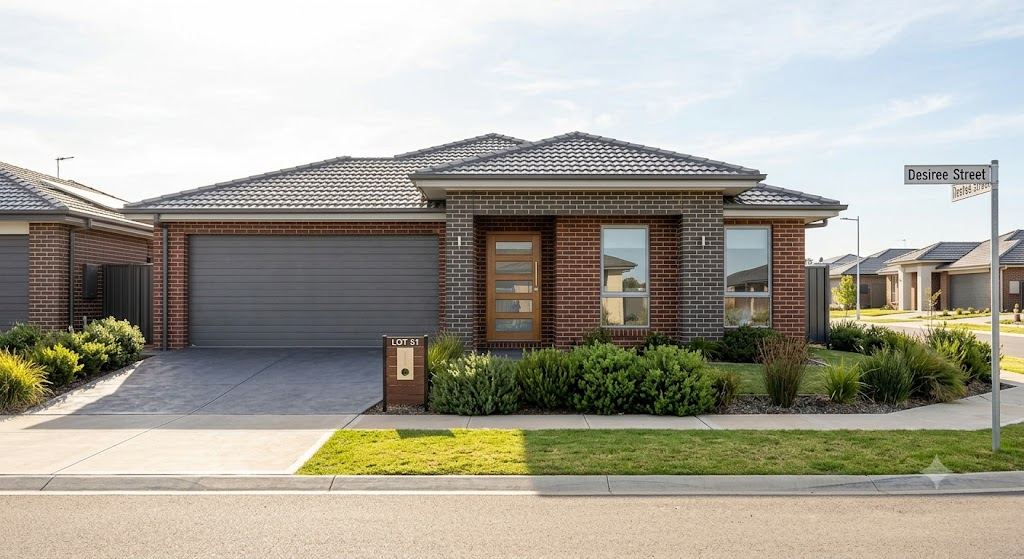 +110% growth
Munno Para, SA
Buy and holdCommon questions
Is borrowing capacity the same as pre-approval?
No. Borrowing capacity is an estimate. Pre-approval is a lender's conditional agreement to lend, based on your application.
Can I increase my borrowing capacity?
Reducing debts and credit limits, and keeping steady income, can help. A broker can tell you which lenders suit your situation.
Does rent count as income?
Usually part of the expected rent is counted. How much varies by lender.
General information only. Not financial or credit advice. Speak with a licensed mortgage broker about your circumstances.